
Wirex Review 2026: Crypto Wallet, Cards & Payments Tested
Wirex Review 2026: Crypto Wallet, Cards & Payments Tested
Wirex is a custodial crypto wallet and payment platform that bundles a multi-currency debit card, an in-app exchange, yield products, and global transfers into one account. It is trusted by roughly 7 million users and issues cards as a principal member of both Visa and Mastercard, which is unusual in the crypto-card market. But the headline "up to 8% cashback" hides a tiered subscription model, a WXT token lockup, and regional restrictions that decide whether Wirex is a great fit or a poor one. This review breaks down the real costs, the setup flow, and the decision criteria.
What Wirex actually is
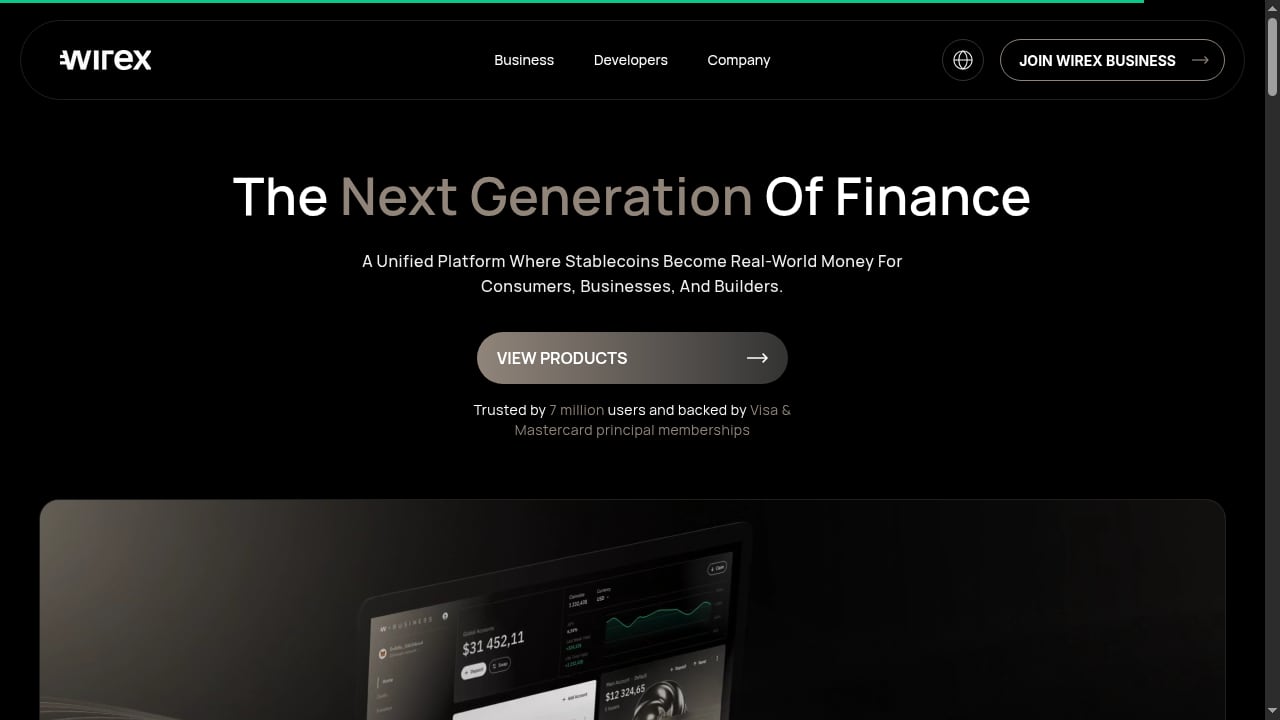
First viewport screenshot of Wirex | Crypto Wallet, Cards & Payments for All.
Wirex is not a single product. It is an ecosystem:
- Custodial wallet — holds 150+ crypto and fiat assets, with Wirex controlling the private keys.
- Preload debit card — you top up fiat or crypto, and crypto converts to your spend currency in-app before the purchase settles.
- Exchange — in-app swaps between supported assets, with conversion spreads shown before you confirm.
- Yield products — X-Accounts marketed with high headline rates, terms depending on plan, asset, and region.
- Credit — stablecoin loans backed by BTC or ETH, availability varies by region and account level.
- Wirex Business — corporate accounts, corporate and payroll cards, and stablecoin settlement for teams.
The card is a preload model, not an auto-sell card. That distinction matters: with an auto-sell card, crypto is liquidated at the register. With Wirex, the conversion and its spread happen on Wirex's side before the transaction settles, so the rate you get is the rate Wirex applies, not the live market rate at the moment of payment.
Who Wirex is for
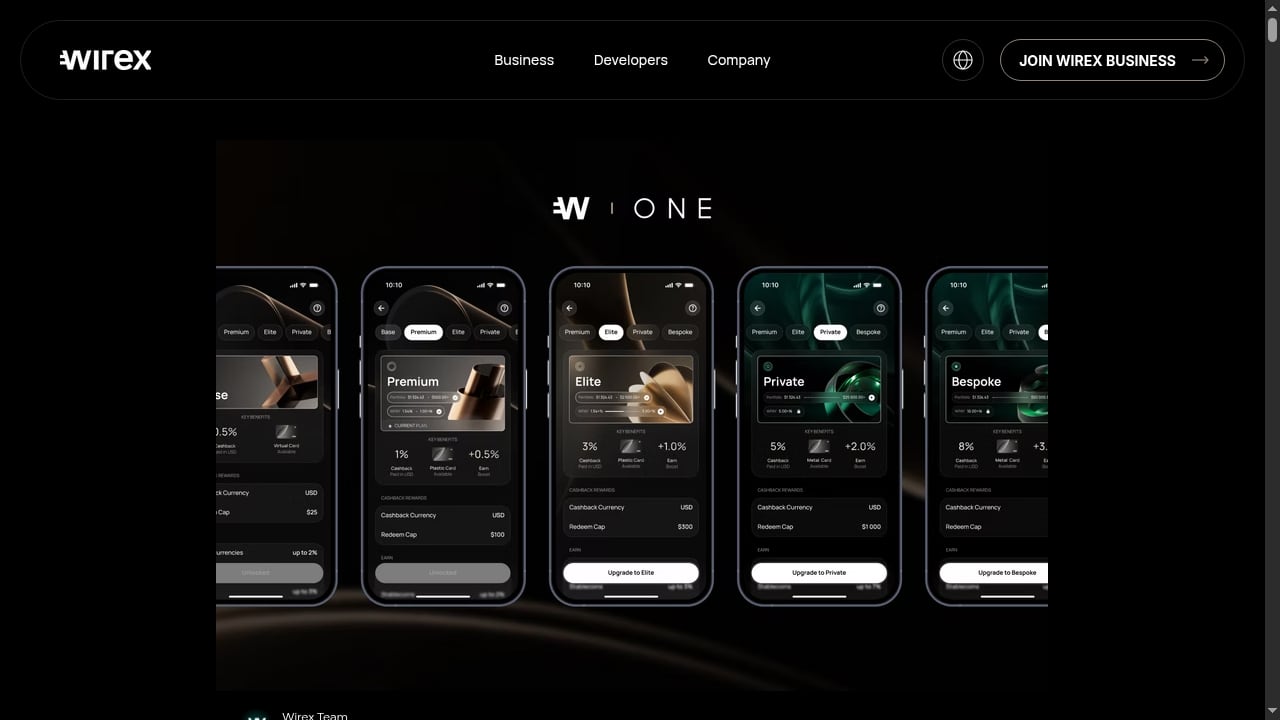
First viewport screenshot of Wirex | Crypto & Web3 Insights, Guides & News.
Wirex fits three broad profiles:
- Frequent travelers and multi-currency spenders who hold several fiat balances and want 0% marketed foreign-transaction fees across 30+ currencies.
- Active crypto users who already keep assets on a custodial platform and want to spend them without moving funds to a separate exchange.
- Small businesses and builders that need stablecoin treasury, corporate cards, and fiat rails in one place.
It fits less well for people who want self-custody, predictable flat costs, or a "fund it once and forget it" setup. Inactivity fees and low fee-free ATM allowances can erode a dormant balance.
Wirex card tiers, cashback, and the real math
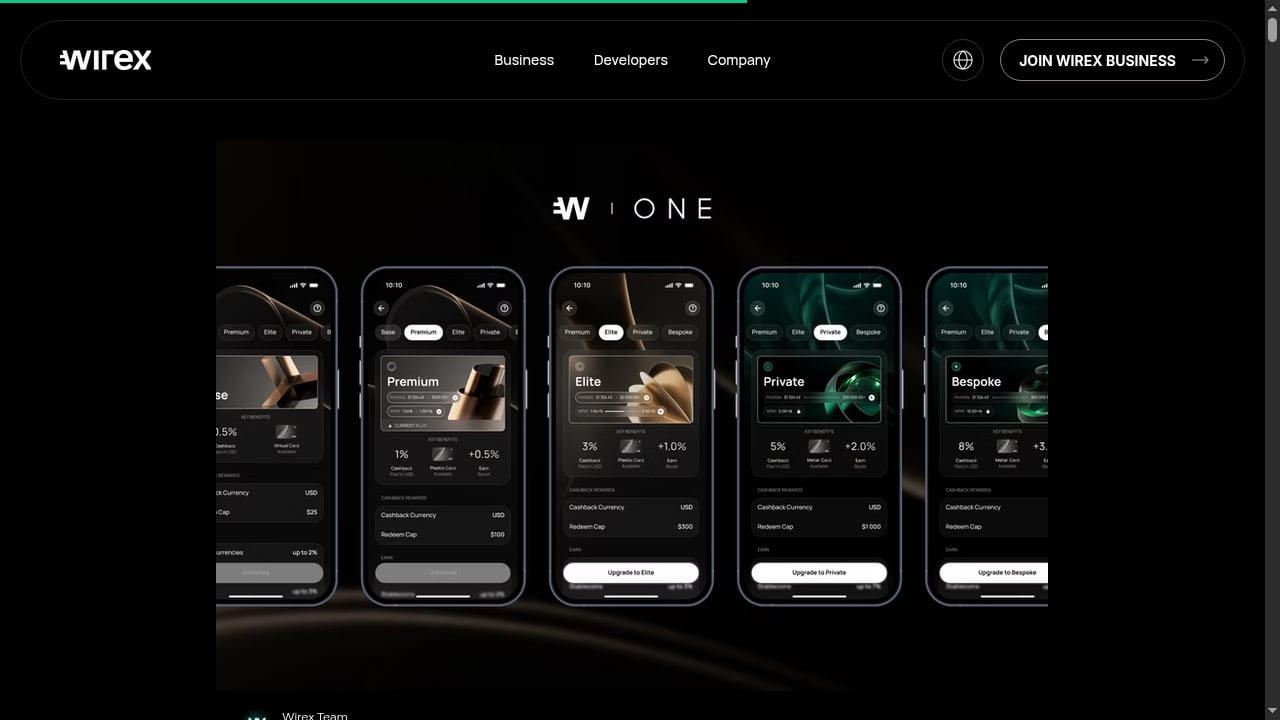
First viewport screenshot of Wirex | Crypto & Web3 Insights, Guides & News | Page 3 of 4.
The advertised 8% cashback is the top of a tiered ladder. Here is how the tiers actually work, based on Wirex's X-tras page and independent card testing:
| Tier | Subscription | Cryptoback | Notes |
|---|---|---|---|
| Standard — Entry | Free | 0.5% | Paid in WXT |
| Standard — Enhanced | Free | 1% | Requires WXT lockup |
| Premium — Entry | €9.99/mo | 1% | |
| Premium — Enhanced | €9.99/mo | 2% | WXT lockup |
| Premium — top tier | €9.99/mo | 3% | WXT lockup |
| Elite — Entry | €29.99/mo | 4% | |
| Elite — Enhanced | €29.99/mo | 6% | WXT lockup |
| Elite — top tier | €29.99/mo | 8% | 7,500,000 WXT locked for 180 days |
Three things compress the effective rate:
- Rewards are paid in WXT, Wirex's own token, so the value floats with the token price. Fiat or stablecoin cashback would carry no such exposure.
- Per-transaction and monthly caps apply. The 8% tier caps at 9,000 WXT per transaction and 250,000 WXT per month.
- Excluded spending includes ATM withdrawals, peer-to-peer transfers, and tax payments.
For a free-tier user, the realized rate is 0.5% in WXT. Reaching 8% requires the Elite subscription (€306/year) plus a very large WXT lockup, which is a capital commitment, not a spending perk. Treat the card as a subscription product, not a standard debit card.
Fees, limits, and the cost profile
| Item | Detail |
|---|---|
| Annual fee | None |
| Card issuance and PIN change | Free |
| Premium subscription | €9.99/mo (€102/yr) |
| Elite subscription | €29.99/mo (€306/yr) |
| Foreign transaction | 0% marketed, 30+ currencies; real cost is the in-app conversion spread |
| ATM withdrawal | Free up to €200/£200/S$200 per month (A$400 in Australia), then 2% |
| Daily purchases | Up to €30,000 (EEA representative) |
| Daily ATM | Up to €500 (EEA representative) |
None of these fees are unusual for a multi-currency card on their own. The catch is that the "free" card and the "rewarded" card are two different cost profiles. Reaching higher Cryptoback tiers means paying for Premium or Elite on top of accepting the conversion spread.
Practical tip: hold a local fiat balance in advance and pay from that balance to reduce conversion losses. Converting at checkout every time adds up.
Setup and onboarding
The flow is familiar:
- Create an account and complete KYC (government ID, and a liveness check in some countries).
- Issue a virtual card instantly in-app; optionally order a physical card.
- Fund the account via bank transfer (SEPA, Faster Payments, ACH, PIX — generally free in most regions), open banking for GBP and EUR, debit or credit card (region-dependent fees), or crypto deposit (free after network confirmations on the correct network).
- Start paying online and in person, with Apple Pay and Google Pay supported.
Physical delivery uses Standard (local post, untracked) or Express (DHL Express, tracked) and may take several days up to roughly four weeks depending on option and region.
Availability and regional restrictions
The card issues in about 35 markets, but the scored product — Classic Wirex with Cryptoback — now operates only in the UK, New Zealand, Hong Kong, and Taiwan. In the EEA and Australia, the card still exists as a fiat debit product, with Wirex One as the sole crypto path going forward. In the EEA, Mastercard eligibility requires EEA residency excluding Cyprus and Liechtenstein.
Not available: United States (account and crypto account only, no card), Canada, China, Japan, South Korea, Singapore, Philippines, Russia, and sanctioned countries.
This regional fragmentation is the single biggest decision factor. Check your country before evaluating anything else.
Security, custody, and freeze risk
Wirex is custodial: the platform holds the private keys for supported crypto balances. That boosts convenience — easier spending, easier swaps — but it means you depend on Wirex's operational reliability and compliance decisions.
The card is issued through regulated, disclosed entities: Transact Payments Malta Limited for the EEA Mastercard program, and Wirex Pte Ltd in Singapore for APAC. That is better than the anonymous-operator end of the crypto-card market.
The near-term risk is the migration itself. The move from the Classic app to Wirex One around June 28–30, 2026 produced reported balance-transfer failures, with stuck transfers queued for reprocessing. If you are in an affected region, confirm balances and accrued rewards arrived intact before relying on the card.
The app supports virtual cards, freeze and spend-limit controls, and Apple Pay and Google Pay. Support is standard in-app help, and the live dispute risk in mid-2026 is the Classic-to-Wirex One migration path.
Wirex vs alternatives: decision criteria
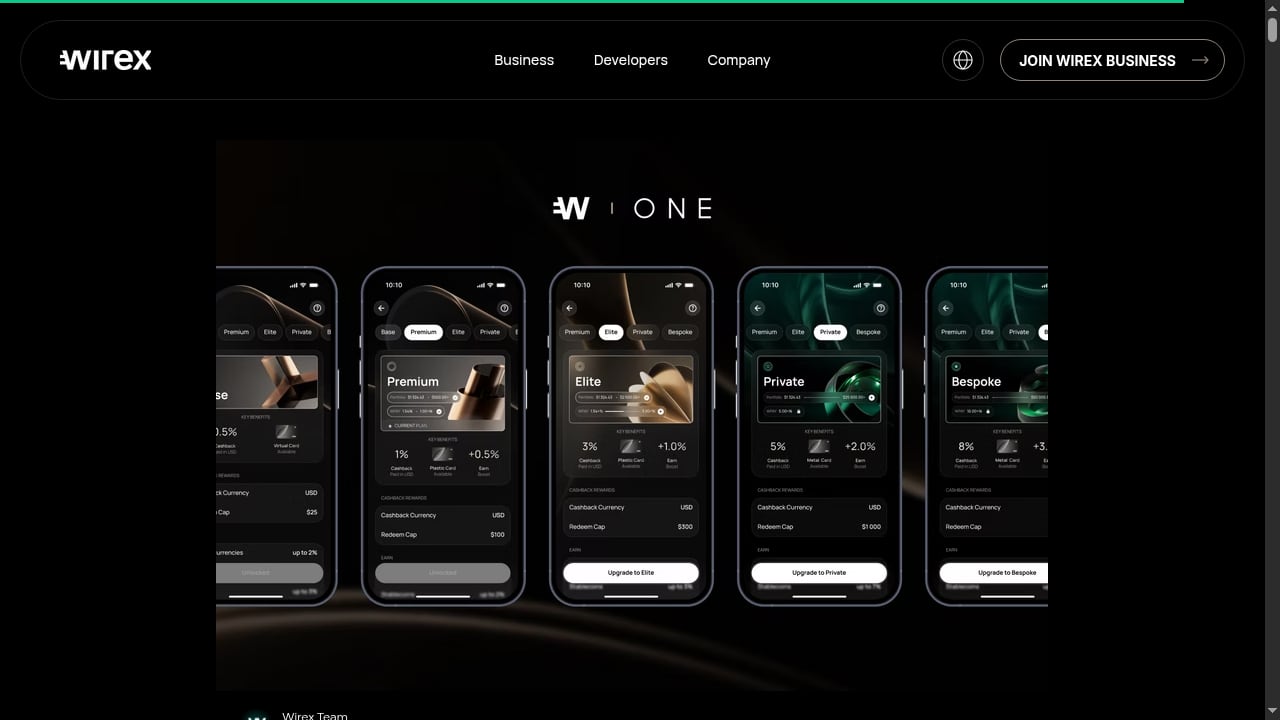
First viewport screenshot of Wirex | Crypto & Web3 Insights, Guides & News | Page 2 of 4.
| If you need... | Wirex fit | Consider instead |
|---|---|---|
| Multi-currency travel spending in UK/NZ/HK/TW | Strong | — |
| Self-custody of crypto | Weak | Self-custody wallets |
| Predictable flat costs | Weak | Simple fiat debit cards |
| Corporate stablecoin treasury + cards | Strong (Wirex Business) | Cryptopay Business for merchant payments |
| Global business accounts with fiat-crypto rails | Moderate | Banxe |
| Corporate crypto cards for teams | Moderate | Cardfornia vs Reap vs Banxe comparison |
For businesses specifically, Wirex Business unifies stablecoins, fiat accounts, and Visa cards with zero FX and instant settlement, plus corporate and payroll cards. If your use case is paying for AI subscriptions or SaaS with stablecoins, see our guide to a crypto card for AI subscriptions.
Strengths and limitations
Strengths
- Wide asset selection: 150+ crypto and fiat assets in one app.
- Strong cashback potential at the top tier (up to 8%, tier-dependent).
- Yield tools (X-Accounts) and stablecoin credit for liquidity without selling.
- Travel convenience: 0% marketed FX across 30+ currencies.
- Free issuance, free PIN changes, and an ATM allowance.
- Regulated, disclosed issuers in each region.
Limitations
- Paid plans are expensive: top perks require a subscription up to €29.99/month plus large WXT lockups.
- Inactivity fees: long periods without activity can lead to recurring charges.
- Custodial risk: the platform holds the private keys.
- Operational limits: daily transaction limits and low fee-free ATM allowances.
- Hidden conversion costs: spreads and markups make FX less transparent.
- Support reputation: complaints about slow resolutions and account freezes.
Related reading
- OneSafe Neo-Banking Review: Global Business Fit & Fees - Evidence-based OneSafe review for global businesses: who it fits, real fee signals, onboarding, DAO and Web3 controls, limitations, and decision criteria.
- Cardfornia Login: Secure Access to Your Crypto Card Account - Learn how Cardfornia login works for corporate crypto card accounts, including access, security, troubleshooting, and how teams manage stablecoin spending.
Sources and further reading
- Wirex | Crypto Wallet, Cards & Payments for All - Wirex is a crypto wallet and payment platform with cards, exchange, yield products, and global transfers — simple, secure, and user-centric.
- Wirex Crypto Card Review 2026: Is the 8% Cashback Rate Real? - Wirex card has no annual fee and advertises up to 8% cashback, but that rate requires locking 7.5 million WXT tokens. Read the full breakdown.
- WIREX visa card review 2026: our verdict after hands-on testing - We tested Wirex Card like a regular user: card issuance, funding, online and in-store payments, currency conversion at checkout across multiple currencies, and ATM cash withdrawals. Along the way, we tracked the real costs: fees, exchange spreads, and limits, plus how quickly support issues get resolved.
FAQ
Is the 8% Wirex cashback real? It is real but conditional. It requires the Elite subscription (€29.99/month) plus a 7,500,000 WXT lockup for 180 days, and it is capped per transaction and per month. Most users will realize far less.
Is Wirex available in the US? No card. US residents can open a Wirex account and crypto account, but Wirex exited the US card market and has not returned.
Does Wirex charge foreign transaction fees? It markets 0% FX across 30+ currencies, but the real cost is the in-app conversion spread, which is shown before you confirm. Stablecoin conversions are close to 1:1; volatile assets carry wider spreads.
Can I use Wirex without crypto? Yes. The app is designed for both crypto users and people who just want better control of their money, with fiat accounts and cards in one place.
What happens if I stop using Wirex? Inactivity fees can kick in after a long period with no activity, shrinking your balance. Occasional transactions keep the account active.
Conclusion
Wirex is a strong fit for travelers and active users in the UK, New Zealand, Hong Kong, and Taiwan who want a multi-currency card with crypto layered on top, and for businesses that need stablecoin treasury plus corporate cards. It is a weak fit for self-custody advocates, US and Canadian residents who want a card, and anyone who wants predictable flat costs without a subscription. Before signing up, verify your country's availability, model the subscription plus WXT lockup against your actual spending, and decide whether WXT-denominated rewards are a feature or a risk for you.
For broader context on how crypto payments and trading work in 2026, see our explainer on how crypto trading works.