
OneSafe Neo-Banking Review: Global Business Fit & Fees
OneSafe Neo-Banking Review for Global Businesses: Fit, Fees, and Limits
OneSafe markets itself as neo-banking for global businesses, Web3 startups, and DAOs that want fiat and crypto operations in one dashboard. That pitch is attractive, but the useful question is narrower: does OneSafe's actual fee stack, legal structure, and control model fit how your company moves money? This review separates marketing language from operational reality, using publicly available fee data, community feedback, and a practical evaluation framework.
What OneSafe actually is
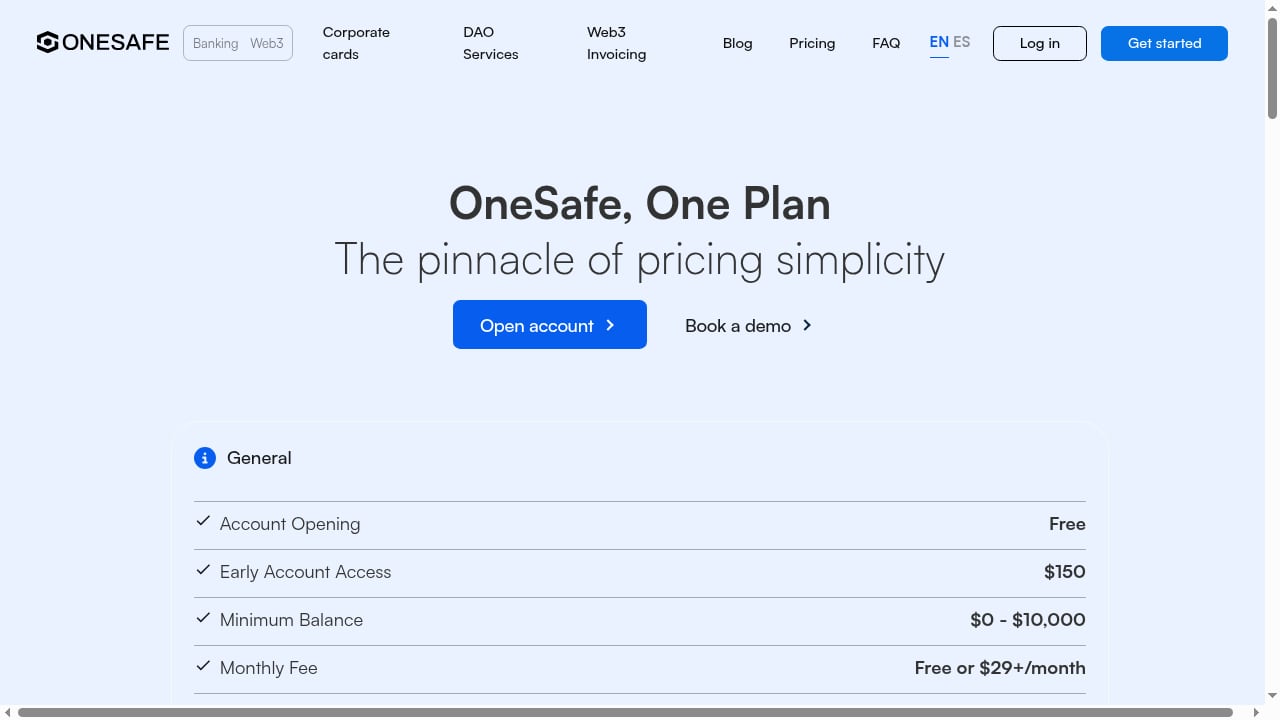
First viewport screenshot of Pricing.
OneSafe is a financial technology company, not a bank. Fiat balances sit with partner banks, while crypto custody is handled through a third-party infrastructure provider. That distinction matters because it determines what protection you actually get:
- Fiat deposits may be eligible for pass-through insurance at the partner bank, subject to that bank's structure and limits.
- Crypto holdings are not insured and carry custody and market risk.
- Operational security (encryption, MFA, custody vaults) is separate from deposit safety (bank resolution, insurance coverage).
If a provider conflates those two, treat it as a warning sign. OneSafe's own materials acknowledge the fintech-versus-bank distinction, which is a point in its favor for transparency.
Who OneSafe is built for
First viewport screenshot of OneSafe | Neo-Banking for global businesses.
OneSafe fits a specific profile better than a general-purpose business account:
Good fit:
- Web3 startups and DAOs that hold stablecoins and need to pay contributors in USDC
- Global businesses with contractors across multiple jurisdictions who want to avoid correspondent-bank delays
- Teams that need multi-signature approvals and role-based permissions on treasury movements
- Companies comfortable with a hybrid fiat-plus-crypto account model
Weaker fit:
- Businesses that only need EUR or USD payments and want full deposit insurance with no crypto exposure
- Companies in jurisdictions OneSafe does not serve, or in excluded US states
- Teams that expect a traditional bank relationship with branch support and full regulatory coverage
Use cases that make sense
Stablecoin payroll for distributed teams
A DAO paying 20 contributors across 12 countries can hold USDC in OneSafe, convert to local fiat where needed, and avoid SWIFT delays. USDC on-ramp and off-ramp are typically free, which is the strongest cost argument for this use case.
Cross-border supplier payments
A business paying a supplier in another currency can compare two paths: a SWIFT transfer at 0.35% plus $50, or a stablecoin transfer settled on-chain. For recurring high-value payments, the stablecoin route is usually cheaper and faster, but it requires the supplier to accept crypto. For more on this trade-off, see our guide to cross-border procurement crypto.
Treasury controls for DAOs
OneSafe supports multi-signature approvals and permissioned roles. That replaces a "quorum vote, then email the wire instructions" process with an auditable dashboard. For DAOs, this is often the deciding feature.
The fee stack in practice
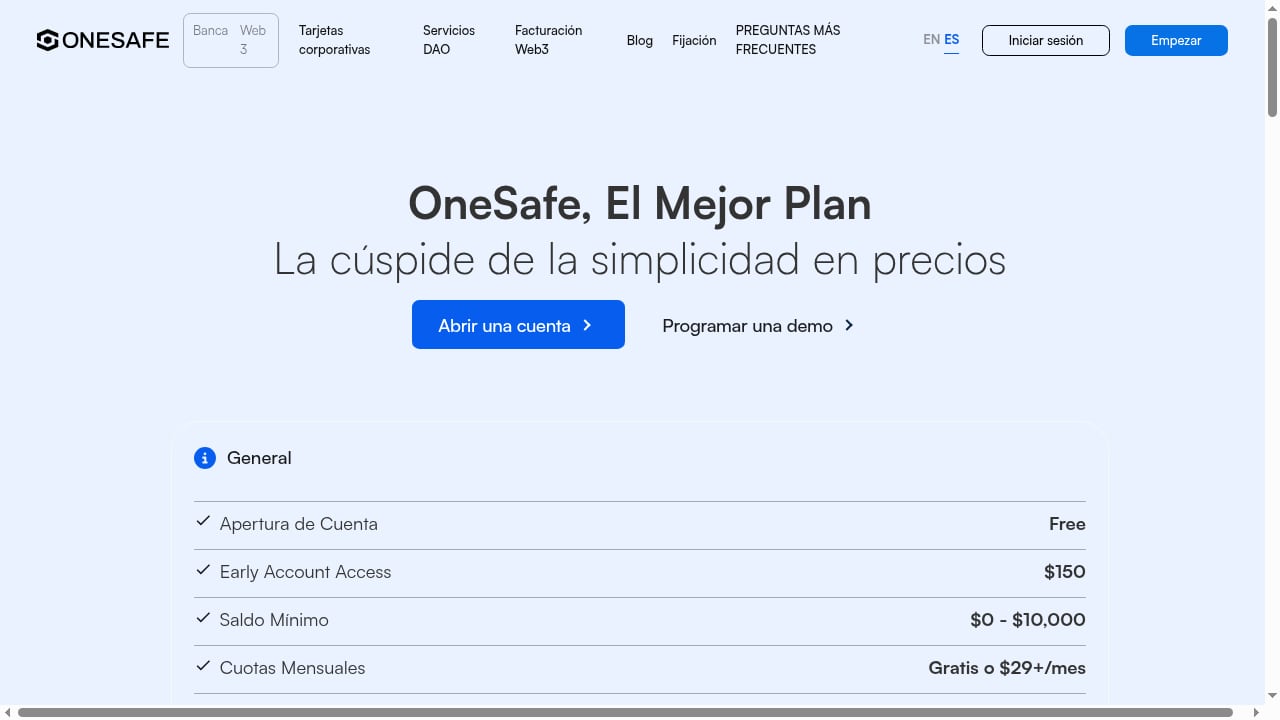
OneSafe publishes a granular fee schedule. The numbers below reflect publicly documented rates and should be re-verified before you commit, since pricing can change.
| Fee category | OneSafe signal | When it bites |
|---|---|---|
| Monthly subscription | Free tier; premium from around $29/month | Higher limits or premium features |
| Fiat deposit/withdrawal | Around 0.15% | Every fiat movement |
| Domestic wire out | Around $25 | Frequent outgoing wires |
| Domestic wire in | Around $10 | Incoming wires |
| SWIFT transfer | Around 0.35% + $50 | Every international wire |
| FX conversion | Around 0.25% or prevailing rate | Fiat-to-fiat conversions |
| Corporate card FX | Around 3% | Foreign-currency card spend |
| USDC on/off-ramp | Free | Stablecoin movement |
Worked example: A $10,000 SWIFT transfer costs roughly $85 before any FX markup. A $5,000 month of foreign-currency card spending loses about $150 to card FX. Run your own monthly totals before choosing.
The 3% card FX fee is the most likely hidden sting. If your team spends heavily in foreign currencies, route those payments through wire or stablecoin instead, or compare against a dedicated corporate card provider such as those covered in our Cardfornia vs OneSafe vs BVNK comparison.
Onboarding and setup
Onboarding is digital and typically completes within about a week, with a short initial application. Expect to provide:
- Certificate of incorporation or equivalent formation documents
- Photo ID for beneficial owners
- EIN for US entities
- Sometimes proof of business activity or source of funds
"Fast onboarding" does not mean no documents. KYB checks are standard, and OFAC-sanctioned countries are blocked. Confirm your jurisdiction and US state eligibility before applying.
Strengths
- Transparent, granular fee schedule — unusual in this category and useful for treasury planning
- Free USDC on/off-ramp — the strongest cost advantage for stablecoin-heavy businesses
- DAO and Web3 controls — multi-sig, role-based permissions, auditable payouts
- Hybrid fiat-plus-crypto rails — one dashboard instead of separate banking and exchange relationships
- 24/7 support — relevant for teams operating across time zones
Limitations and risks
First viewport screenshot of Blog.
- Not a bank — deposit protection depends on the partner bank, not OneSafe's brand
- Crypto custody risk — no insurance on crypto holdings; theft protection is not market protection
- 3% corporate card FX — expensive for foreign-currency spenders
- SWIFT cost — 0.35% + $50 adds up for frequent international wires
- Community skepticism — public forum discussions have questioned the marketing language and the Las Vegas address, which appears to be a mailbox-style location. That is common for IT companies but worth verifying independently.
- Regulatory backdrop — the Financial Stability Board's October 2026 peer review flagged incomplete resolution backstop funding at some banks, which can delay access to fiat even when deposits are insured. Where your fiat is banked matters as much as the fintech front-end.
How OneSafe compares to alternatives
First viewport screenshot of Precios.
| Provider type | Example | Best for | Main trade-off |
|---|---|---|---|
| Fintech with crypto rails | OneSafe | Web3 teams, DAOs, stablecoin payroll | Custody risk, partner-bank dependence |
| Crypto card platforms | Cardfornia | Stablecoin-funded corporate card spend | Less fiat banking depth |
| Crypto-native platforms | BVNK | Global payment infrastructure | Different onboarding and control model |
| Traditional banks | HSBC, Chase | Full insurance, branch support | Slow onboarding, limited crypto |
If your priority is a corporate card funded by stablecoins with strong team controls, a dedicated card provider may fit better. See our Cardfornia vs OneSafe vs Sparados comparison for a side-by-side view.
Decision checklist
Before choosing OneSafe, verify:
- Fee transparency — every wire, SWIFT, card-FX, and crypto spread
- Onboarding requirements — formation docs, ID, EIN, KYB timeline
- Geographic eligibility — countries served, US state restrictions, OFAC screening
- Fund segregation and custody — partner bank, FDIC pass-through, crypto custody provider
- Fiat-crypto rails — supported on/off-ramps, stablecoin inventory, conversion speed
- DAO and Web3 controls — multi-sig, role-based permissions, automated payouts
- Regulatory posture — licenses, sanctions screening, AML program
- Operational versus deposit safety — encryption and MFA versus insurance and resolution backstop
Related reading
- Cardfornia Login: Secure Access to Your Crypto Card Account - Learn how Cardfornia login works for corporate crypto card accounts, including access, security, troubleshooting, and how teams manage stablecoin spending.
- Cardfornia vs Reap vs Banxe: 2026 Crypto Card Comparison - Compare Cardfornia, Reap, and Banxe for corporate crypto cards in 2026: stablecoin funding, virtual card issuance, multi-currency spend, and team controls.
- Crypto Card for AI Subscriptions: 2026 Business Guide - How businesses use a crypto card for AI subscriptions like ChatGPT, Claude, and Midjourney: stablecoin funding, Stripe acceptance, team controls, and fees.
Sources and further reading
- Read Customer Service Reviews of onesafe.io - Trustpilot - Jun 4, 2025 ... How is the TrustScore calculated? No recent history of asking for reviews. This company hasn't invited customers recently, so ...
- onesafe.io reviews : r/digitalnomad - Sep 5, 2025 ... "Banking web3", "Redefining global finance", "Unlock the potential", "not a bank", "crypto native business". Hell no. GiveMeYourSmile. OP •. 1y ...
- Global Finance Accounts Reviews: A Buyer's Guide - Global finance accounts reviews: evaluate providers, compare fiat+crypto fees, and avoid hidden costs. A practical guide for founders and finance leads.
FAQ
Is OneSafe a bank? No. OneSafe is a financial technology company. Banking services are provided by partner banks, and crypto custody is handled by a third-party provider.
Is my money insured at OneSafe? Fiat deposits may be eligible for pass-through insurance at the partner bank, subject to limits. Crypto holdings are not insured.
How long does OneSafe onboarding take? Digital onboarding typically completes within about a week, after submitting formation documents, ID, and EIN for US entities.
What does OneSafe cost? There is a free tier and premium plans from around $29/month. Fiat movements cost about 0.15%, domestic wires $10–$25, SWIFT 0.35% + $50, FX around 0.25%, and corporate card FX around 3%. USDC on/off-ramp is typically free.
Who should not use OneSafe? Businesses that only need simple fiat payments, want full deposit insurance with no crypto exposure, or operate in ineligible jurisdictions may be better served by a traditional bank or a fiat-only fintech.
Does OneSafe work for DAOs? Yes. It supports multi-signature approvals, role-based permissions, and native stablecoin holdings, which are core requirements for DAO treasury management.
Conclusion
OneSafe is a credible option for global businesses, Web3 startups, and DAOs that want fiat and crypto operations in one place. Its transparent fee schedule and free USDC rails are real advantages. The trade-offs are equally real: it is not a bank, crypto is not insured, the 3% card FX fee is expensive, and SWIFT costs add up. The right decision depends on your payment mix. If most of your volume is stablecoin-based, OneSafe's economics work well. If most of your volume is foreign-currency card spend or simple fiat wires, compare against a dedicated corporate card provider or a traditional bank before committing.